

Imagine getting a salary without actually having to work for it. No office to rush to. No boss to report to. No targets to chase. Just more time for the things that matter to you. Sounds great, right?
You spend years saving money to build your investments. There comes a point in time when you want those investments to support you - give you a monthly income that manages your expenses. That’s where a Systematic Withdrawal Plan (SWP) comes in.
In other words, you do not just build a portfolio. Eventually, you make it pay you.
You may have heard a lot about SWP; today we break it down for you.
Let us begin with what is an SWP?
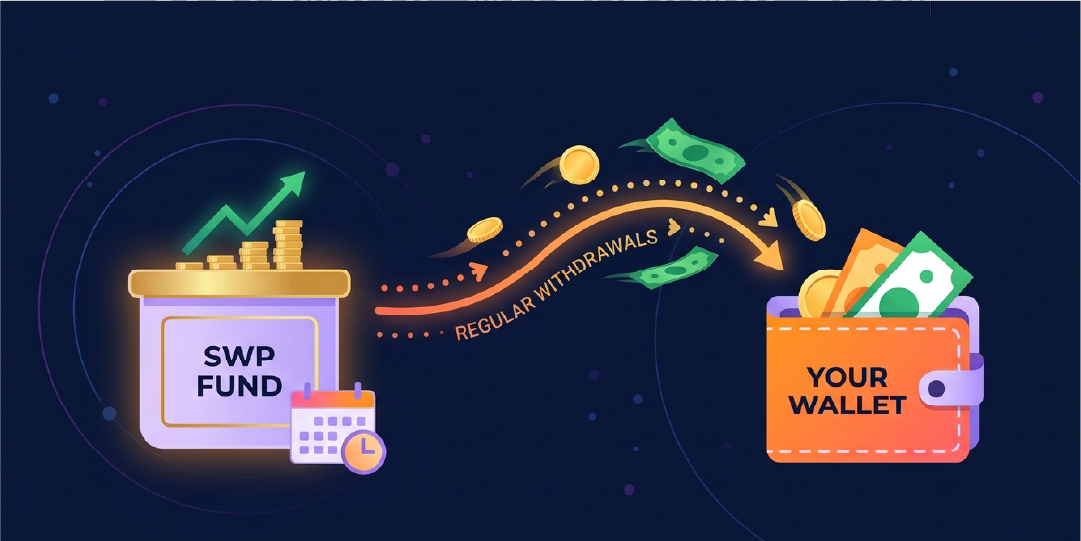
An SWP, is a facility provided by mutual funds to regularly withdraw a fixed amount of money at a fixed frequency for a predetermined period of time. Say for example, you have an accumulated corpus of Rs. 10 lakhs, you can consider taking an SWP facility to get Rs. 5,000 on 1st of every month for the next 3 years.
Think of it as the reverse of an SIP.
With an SIP, a fixed amount is deducted from your bank account on a fixed date and goes into your investments. With an SWP, a fixed amount is redeemed from your investments on a fixed date and deposited into your bank account.
IDCW instead of SWP: what’s the difference?
Investors have more than often confused an SWP with dividend. In fact, SEBI reclassified the dividend option as “Income Distribution cum Capital Withdrawal” (IDCW) to clarify that pay outs can include return of capital, and not just income earned. Fundamentally, both involve money being paid out but under IDCW, the fund house decides when and how much to distribute. In an SWP, the decision is in the hands of the investor.
The other difference is taxation. The payout from an IDCW is taxed at the income tax slab rate. So, for someone in the 30% slab, this means that a huge part goes towards tax, whereas in an SWP, only the profit of the withdrawal is taxed and that too as capital gains (long term or short term as the case maybe).
The table below compares HDFC Balanced Advantage Fund’s IDCW Payout and Regular Growth plan with SWP, assuming ₹10 lakh invested in each on 1 January ‘14, with pay outs and withdrawals (6% p.a.) starting immediately.
Note: LTCG tax is exempted on gains before 31 January 2018. But, to remain relevant, we apply current tax rules. Surcharge & Cess excluded. Data as on 30-Sept-2026 Source: ACE MF
How does it compare to an FD?
Let’s say you had invested the same ₹10 lakh in a fixed deposit earning 7% annually for 10 years. How would this compare with an SWP with a 7% p.a. withdrawal rate over the same period?
Note: Withdrawals happen for 10 years. SWP considered for HDFC Balanced Advantage Fund. Data as on 30 Sept 2026. Source: ACE MF
An FD has three major limitations when compared to SWP. First, the entire interest is taxed at your tax slab rate, reducing your post-tax returns. At 30% tax rate, a 7% return works out to just 4.9% post tax.
Second, your original corpus does not benefit from capital appreciation. If you invest ₹10 lakh, you receive the principal back at maturity, along with the interest earned. In the above example, not only have you withdrawn the amount every month, you have paid lesser tax and the corpus is also 1.3x more.
So, how can you make SWP into an effective cash flow strategy?
For an SWP to work effectively, it needs to address three crucial requirements: regular cash flow, inflation management and tax efficiency. Let’s see how we can structure a strategy to account for all three.
We assume ₹10 lakh is invested in HDFC Balanced Advantage Fund on 1 January 2014, using the same assumptions as before.
1. Cash flow: build a cushion first
Markets do not move in a straight line, so, to avoid withdrawals eating into the corpus, investors should leave the investment untouched till it grows by 20%. This creates a cushion before withdrawals begin. In this example, it took ~6 months to grow 20%. But the waiting period can be shorter or longer depending on market movements.
2. Determine your monthly cash flow
You need to be careful how you determine your monthly requirement. Ideally, it should be equivalent to what you would withdraw as a fixed deposit (so post tax would be around 5% pa). Since there would be capital gains tax, assume to withdraw 6%pa. Aggressive withdrawal can deplete the corpus, so every investor should be cautious.
3. Inflation management: step up your withdrawals
Your expenses are not going to stay the same forever. A step-up SWP increases the withdrawal amount each year to keep your income in line with the rising costs. We assume a 7% annual increase, slightly above headline inflation.
4. Tax efficiency: pay tax on gains, not the entire withdrawal
In an SWP, investors are selling units of their mutual fund when they withdraw money. Unlike IDCW payouts, where the full payout is taxed, in an SWP the entire withdrawal is not taxable. Tax applies to the capital gains portion of the units redeemed.
What does this strategy deliver?
Putting these principles together, let’s look at how the SWP plays out in our example.
Note: Data as on 30-Sept-2026. Source: ACE MF
Over the first 10 years, you would have withdrawn approximately ₹8.3 lakh, while the remaining corpus continued to participate in market growth. The remarkable part? Even after regular withdrawals, which were stepped up every year, the corpus grew more than 2x its value.
A 6% SWP looks smooth on paper, but the fund does not move in a straight line. In 2018, the NAV saw a sharp fall of 6.4%, yet the invested value remained at around ₹17 lakh. The March 2020 crash was a major challenge, where the NAV fell by ~22%, but the invested value fell from ~17Lakh to only ~13 Lakh. This highlights the importance of waiting for the cushion to build as even such a big fall did not eat into our invested amount.
The Bottom Line
The biggest advantage of an SWP is its tax efficiency, but this strategy isn’t a one-size-fits-all solution. For investors seeking regular income, an SWP can be an extremely powerful tool.
Investors in lower tax brackets, or those who pay no income tax, may be comfortable with the IDCW strategy. But that has a trade-off: the fund house decides when to distribute money and how much.
With an SWP, you call the shots. You decide how much to withdraw and how often, while managing your tax liability efficiently and also stepping up withdrawals to keep pace with inflation. Ultimately, an SWP puts you in the driver’s seat, giving you greater control over how your investments support your financial needs.