Summary:
Ambuja Cements has announced a ₹14,500 crore expansion programme to add around 30 MTPA of grinding capacity and target 155 MTPA by FY30. The investment aims to strengthen regional reach, improve manufacturing efficiency and reduce logistics costs amid margin pressures.
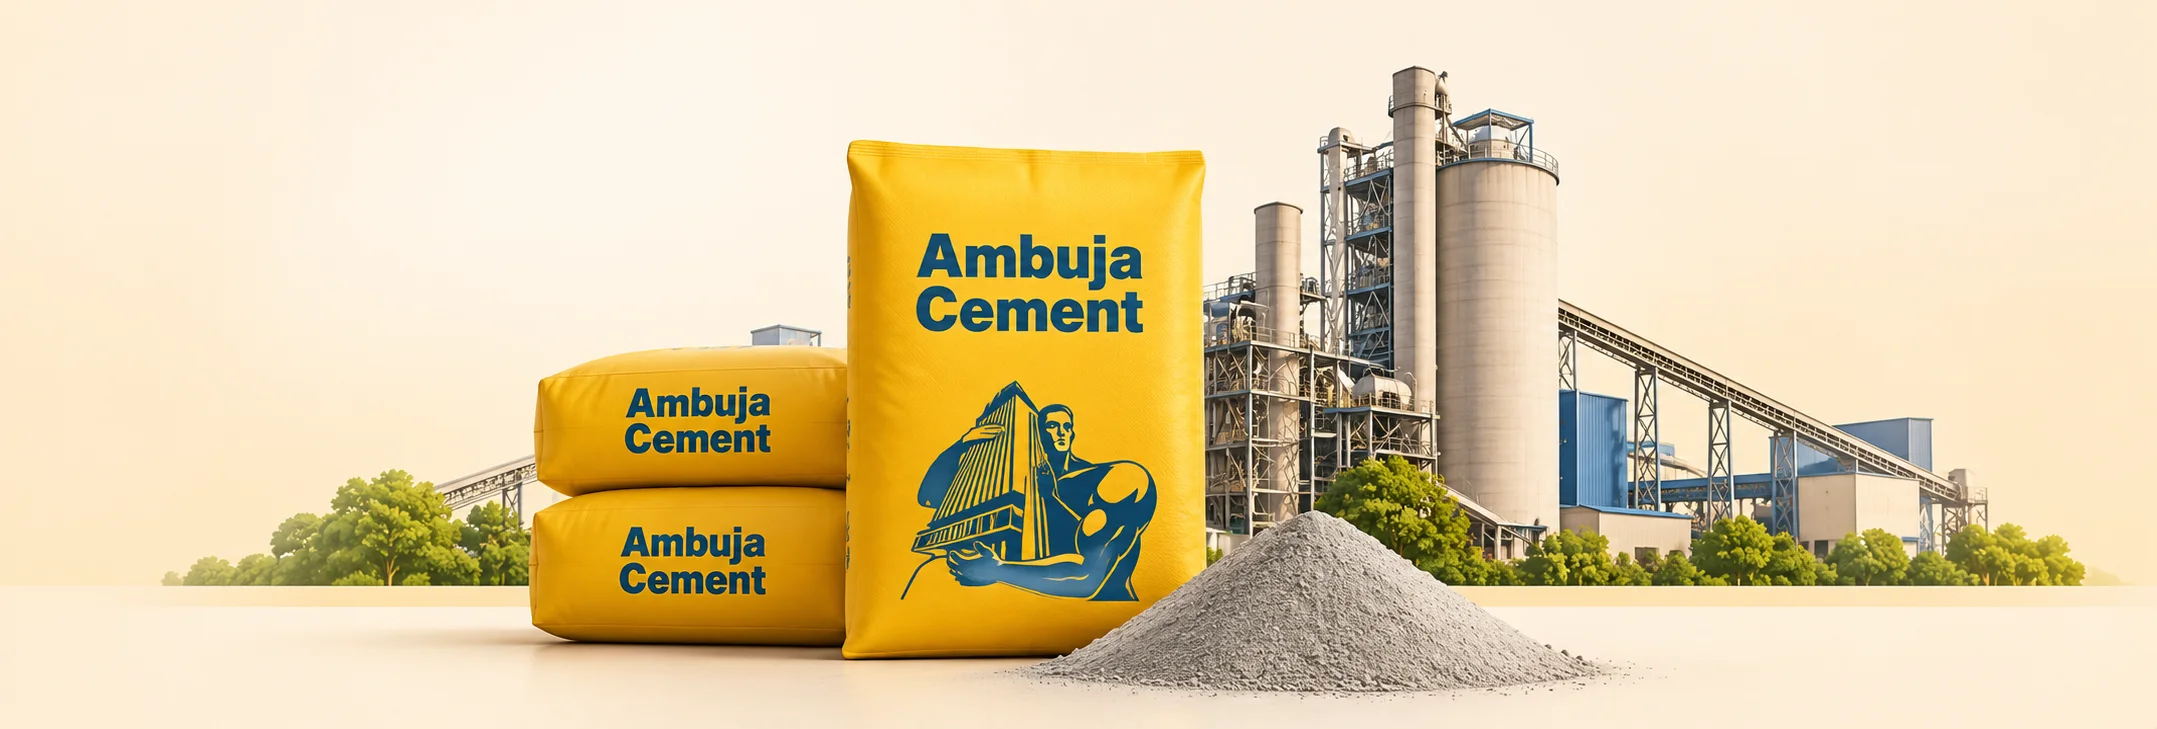
Ambuja Cements Limited (NSE: AMBUJACEM, BSE: 500425) on November 2, 2026 announced a capital expenditure plan of ₹14,500 crore to ramp up cement manufacturing capacity to 155 million tons per annum (MTPA) by FY30. The company hopes to increase production by around 30 MTPA from new projects in eastern, western and northern India, thereby widening its production network.
Ambuja Cements to touch 155 MTPA capacity by FY30
Ambuja Cements today has a total cement capacity of 113.5 MTPA. The proposed expansion, in addition to existing projects and debottlenecking initiatives, will take the total capacity to 155 MTPA by FY30.
The company has planned new green and brownfield projects in Assam, Bihar, Jharkhand, Gujarat, Maharashtra and Uttar Pradesh.
The expansion includes 15.5 MTPA of grinding capacity in western India, 11.6 MTPA in eastern India and 2.9 MTPA in northern India.
| Expansion area | Additional grinding capacity |
| Western India | 15.5 MTPA |
| Eastern India | 11.6 MTPA |
| Northern India | 2.9 MTPA |
| Total | 30 MTPA |
Under the program, there is also additional clinker capacity of 4 MTPA at Umrangso in Assam, 4 MTPA at Maratha and 2.3 MTPA at Mundra.
The projects are intended to improve the production of cement and reduce transportation costs by placing facilities near large markets for consumption.The
Capacity to touch 119 MTPA by March 2027
Ambuja Cements has already set up 4.6 MTPA of incremental capacity in H1FY27.
This included a 1.2 MTPA expansion at Dahej in Gujarat, 2.4 MTPA grinding unit at Salai Banwa in Uttar Pradesh and 1 MTPA at Kalamboli in Maharashtra.
We expect another 5.6 MTPA to come on stream/ramp up in H2FY27 taking total capacity to around 119 MTPA by March 2027.
The company is also aiming to bring down its operating cost to ₹4,000 per ton by FY28 through manufacturing efficiencies and lower logistics costs.
Q2FY27: Revenue Up, Profitability Down
The expansion comes after Ambuja Cements announced its Q2FY27 results on October 29, 2026.
Consolidated revenue from operations came in at ₹9,197 crore as against ₹9,175 crore in Q2FY26, registering marginal YoY growth.
Operating EBITDA came down by 27.9% YoY to Rs 1,271 crore against Rs 1,762 crore. EBITDA margin decreased to 13.8% from 19.2%.
Cement sales volume was 16.5 million tons against 16.6 million tons a year earlier.
Higher fuel and freight costs and weaker seasonal demand cut into profits. The company’s operating cost for the quarter was ₹4,410 a ton.
Ambuja Cements Shares Rise 3.49%. On What Grounds?
Ambuja Cements shares were up 3.49% on November 2, closing at ₹360.20 as against previous close of ₹348.05.
The stock touched an intra-day high of ₹366.40 with around 54.28 lakh shares changing hands.
The stock jumped after the company announced an expansion of ₹14,500 crore and the broader equity market also gained. But it is not possible to isolate the precise impact of the expansion news on the share-price movement.
What’s next for Ambuja Cements?
Cement industry in India continues to be supported by infrastructure development, housing construction and urbanization.
The expansion of Ambuja’s operations could help it reach more markets and improve its manufacturing efficiency over the next few years.
Financial performance, however, will be affected by project execution, capacity utilization, cement prices and energy costs.
Taking the target to 155 MTPA by FY30 is a big jump from the current base of 113.5 MTPA and the planned capacity additions and cost reductions are still big operational milestones.