Summary:
Financial sector credit growth could reach 12–14% in FY27 despite rural risks, weak monsoon concerns and tighter rates. RBI data shows non-food bank credit grew 18.8% in August, while agriculture, industry and NBFC lending also remained strong.
India’s financial sector could see credit expand by 12-14% in FY27, supported by resilient domestic demand, improving private investment and healthy balance sheets across lenders. However, weaker rural incomes, weather-related risks and stress in select borrower segments remain key factors to watch.
Financial Sector Credit Growth FY27
| Indicator | Latest Data / Outlook |
|---|---|
| FY27 financial-sector credit growth outlook | 12–14% |
| Non-food bank credit, August 2026 | 18.8% YoY |
| Agriculture & allied credit | 17.2% YoY |
| Industrial credit | 18.2% YoY |
| NBFC credit | 15.8% YoY |
| Q1 FY27 GDP growth | 7.8% YoY |
| RBI FY27 GDP forecast | 7.1% |
| RBI repo rate | 5.50% |
| Key risk | Rural income and lending stress |
The outlook comes at a time when actual system-wide lending growth is running considerably faster. RBI data showed non-food bank credit rising 18.8% YoY in August 2026, compared with 10.2% in the corresponding period a year earlier.
Financial Sector Credit Growth Could Reach 12–14% in FY27
The latest RBI data points to strong lending momentum across several parts of the economy.
As of the fortnight ended August 31, 2026:
| Segment | Credit Growth YoY |
| Non-food bank credit | 18.8% |
| Agriculture & allied activities | 17.2% |
| Industry | 18.2% |
| NBFC credit | 15.8% |
Bank credit to agriculture and allied activities grew 17.2% YoY, compared with 7.6% in the corresponding period last year. Industrial credit also strengthened sharply to 18.2%, versus 7% a year earlier.
The NBFC segment has also maintained healthy momentum. RBI data for August showed credit extended by NBFCs rising 15.8% YoY, up from 10% in August 2025. Agriculture-linked NBFC credit increased 17.4%, although industrial lending by NBFCs grew at a more moderate 8.4%.
Rural Economy Remains the Key Risk
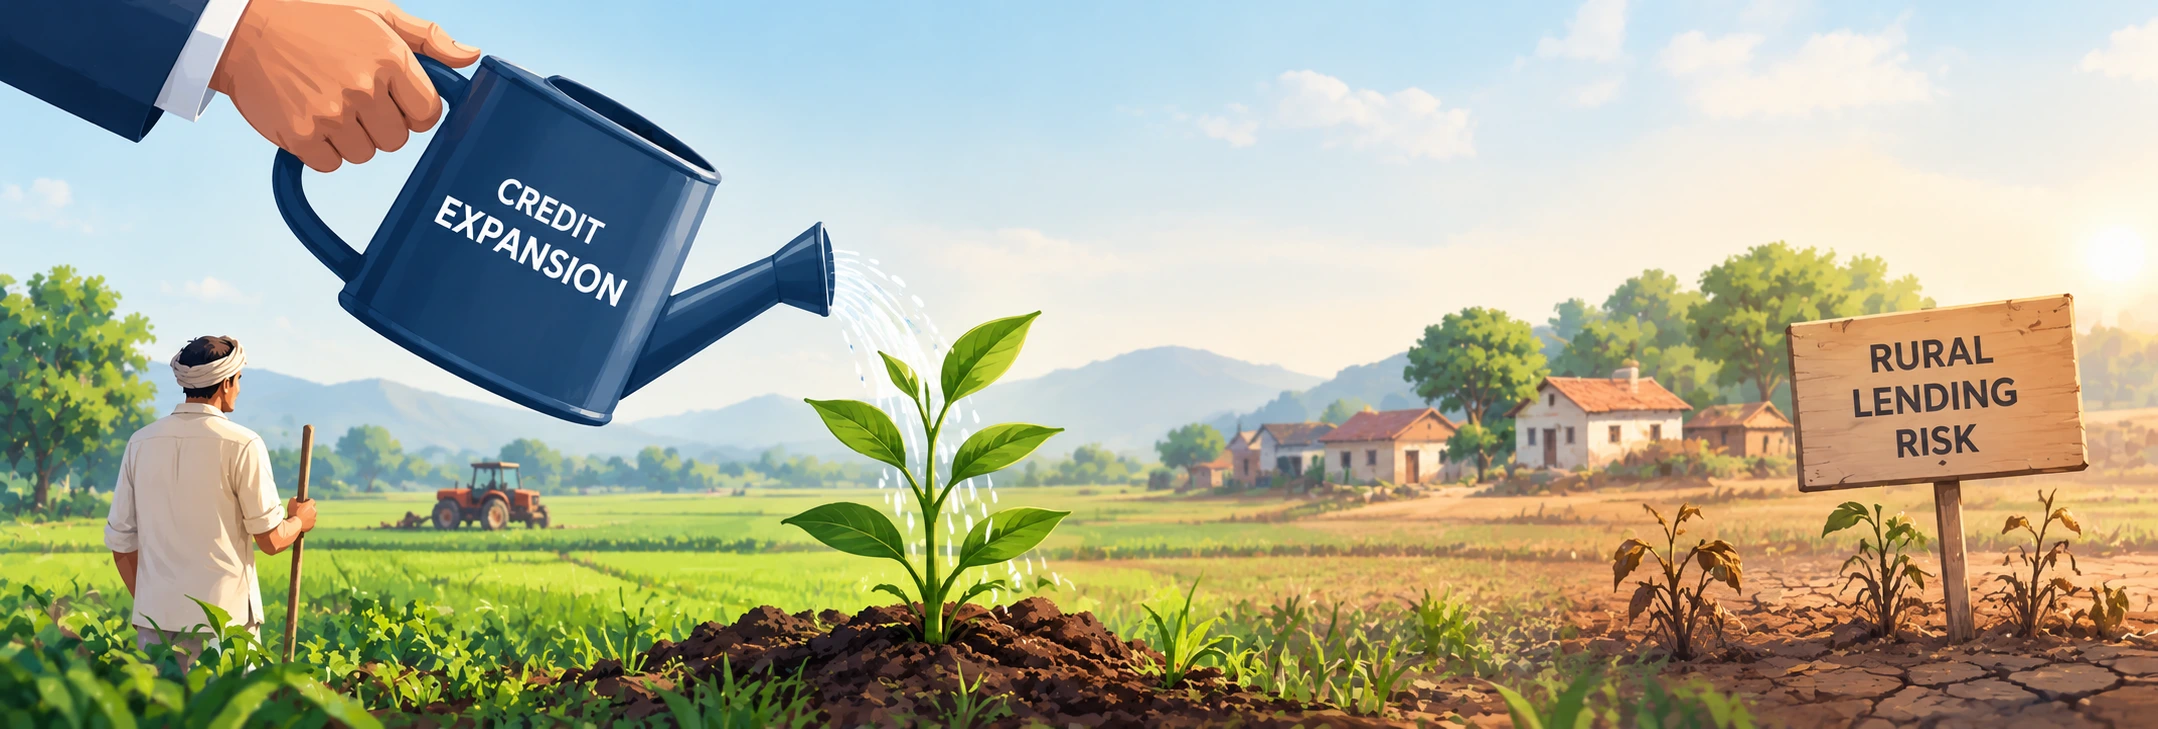
Despite the strong headline numbers, the rural lending environment could become more challenging if irregular rainfall affects farm output and household incomes.
Around one-fourth of bank loans are linked to rural markets, making agricultural income and rural consumption important drivers for lenders. Weak monsoon conditions can affect repayment capacity, fresh borrowing demand and asset quality, particularly among lower-income and self-employed borrowers.
The areas requiring closer monitoring include unsecured retail loans, micro & small enterprises, microfinance, affordable housing and commercial vehicle finance, where borrower cash flows can be more sensitive to rural income conditions.
At the same time, RBI’s latest data indicates that agriculture credit has continued to grow strongly so far, suggesting that any deterioration has not yet translated into a broad slowdown in lending.
Economic Growth Supports Lending Demand
India’s broader economic backdrop remains supportive for credit demand.
Real GDP expanded 7.8% YoY in Q1FY27, while the RBI has raised its FY27 growth forecast to 7.1% following stronger-than-expected activity.
Public investment remains steady, while private capital expenditure has improved in selected areas such as data centres and semiconductors. This provides opportunities for lenders across corporate, infrastructure and project finance.
However, inflation remains an important counterweight. Higher food and energy costs can reduce household disposable income and affect consumption-linked borrowing.
Higher Rates Add a New Variable
The lending outlook also comes after the RBI raised the repo rate by 25 bps to 5.50% on October 7, 2026, its first increase since February 2023.
Higher policy rates can improve yields on some floating-rate loans, but they can also increase borrowing costs and slow demand if rates remain elevated.
For the financial sector, FY27 therefore presents a mixed picture: credit growth remains strong and economic activity supportive, but rural stress, inflation and tighter monetary conditions could influence the pace and quality of lending over the coming quarters.
What Does Strong Credit Growth Mean for Banks and NBFCs?
Strong loan growth can support revenue and net interest income for lenders, but credit growth alone does not determine profitability.
Investors should also track:
- Net interest margins
- Deposit growth
- Cost of funds
- Asset quality
- Gross and net NPAs
- Credit costs
- Provisioning
- Capital adequacy
- Loan mix
- Collection efficiency
A lender growing loans rapidly but experiencing rising delinquencies may not necessarily deliver better shareholder returns.
This makes the quality and profitability of credit growth as important as the headline growth rate.