Summary:
Indian shares rose on Monday, driven by a partial rebound in information technology stocks after recent sharp losses and strong gains in Sun Pharma following its announced $11.75 billion acquisition of U.S.-listed drugmaker Organon. The Nifty 50 was up 0.67% at 24,057.45 and the BSE Sensex added 0.67% to 77,183.24 as of 10:30 a.m. IST.
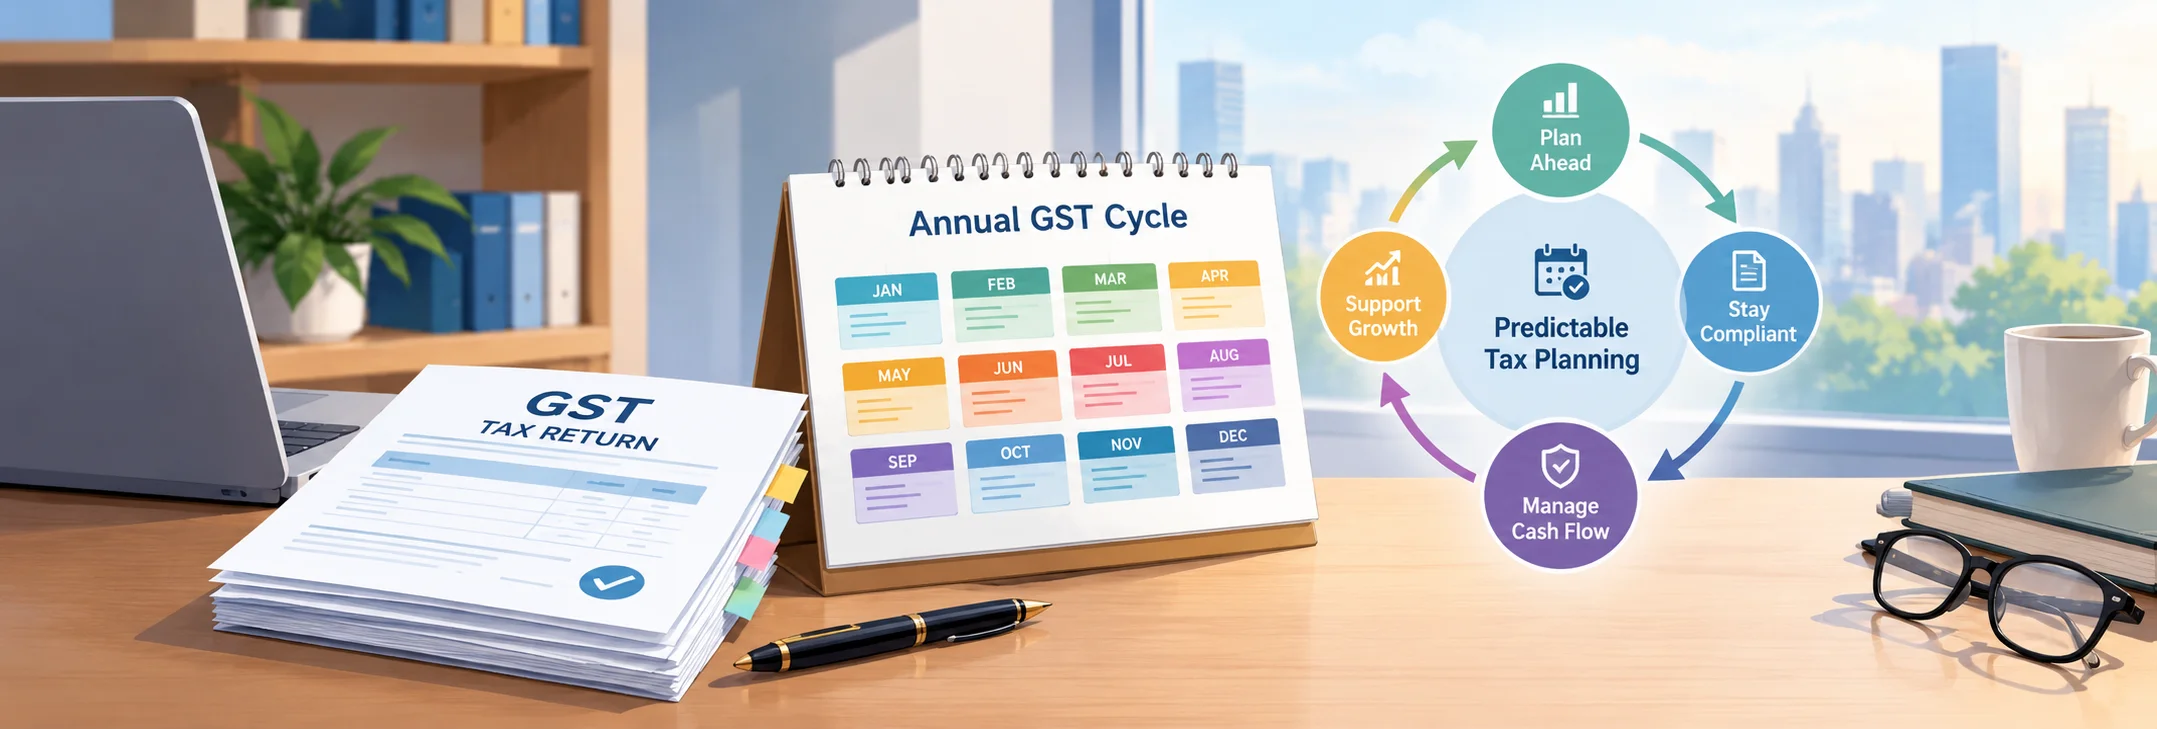
India’s Goods and Services Tax framework could move towards a more predictable annual rate-review system, with future changes likely to take effect from April 1 each year instead of rates being revisited frequently at GST Council meetings.
The proposal comes as the second-generation GST reforms move beyond rate rationalisation towards process simplification, automation and easier compliance for businesses.
| Question | Answer |
| Could GST rates be revised annually? | Yes, an annual review framework is being considered |
| When could changes take effect? | Potentially April 1 each year |
| Will the GST Council stop meeting regularly? | No |
| Will every GST Council meeting involve rate changes? | Not necessarily |
| What could be the next reform focus? | Compliance, automation and process simplification |
| Why does it matter? | Businesses could get greater pricing, inventory and tax-planning certainty |
GST May Get a More Predictable Rate Calendar
The key change being considered is a structured timetable for GST rate revisions. Rather than discussing tax rates at multiple GST Council meetings during a year, major revisions could be considered once annually and implemented from the beginning of a new financial year.
The GST Council is still expected to meet periodically, including on a quarterly basis where required, but every meeting may no longer involve changes to tax slabs or individual product rates.
Such a framework would bring GST closer to the way many direct-tax changes are generally announced around the Budget and implemented from April 1.
For businesses, a fixed annual cycle could make pricing, inventory planning, contracts, tax systems and working-capital management more predictable.
Key Points
| Particulars | Proposed Direction |
| GST rate revisions | Likely once a year |
| Possible effective date | April 1 |
| GST Council meetings | Expected to continue periodically |
| Rate discussions | May not happen at every meeting |
| Focus of next phase | Compliance & process reforms |
What Happened in the 2025 GST Rate Rationalisation?
The groundwork for a more stable regime was laid through the major GST rationalisation approved at the 56th GST Council meeting on September 3, 2025.
The earlier 4-tier structure of 5%, 12%, 18% & 28% was simplified into two principal rates of 5% and 18%, along with a special 40% rate for select de-merit and luxury categories. Most revised rates became effective from September 22, 2025.
Several consumer-facing sectors benefited from the restructuring. GST on products such as shampoos, toothpaste and multiple household items was reduced to 5%, while a number of food products were also moved from 12% or 18% to 5%. Individual life and health insurance policies were granted GST exemption under the reform package.
Sector-specific changes were also substantial. GST on commercial goods vehicles was lowered from 28% → 18%, while rates on several textile inputs, footwear, paper products and other goods were rationalised.
Why Could GST Rate Changes Move to April 1?
An annual implementation date could provide businesses with greater certainty when planning for a new financial year.
A predictable GST rate calendar could help companies:
- Update ERP and billing systems in advance
- Revise product prices systematically
- Plan inventory around tax-rate changes
- Update contracts and commercial agreements
- Assess input tax credit implications
- Prepare invoices and tax documentation
- Manage working capital more efficiently
The key benefit would be predictability, rather than simply reducing the number of GST Council meetings.
Process Reforms Could Be the Next Big Step
With the rate structure significantly simplified, the next phase of GST reform is expected to focus more heavily on administration and compliance.
The proposed system is aimed at increasing automation across areas such as:
- GST registration
- Return filing
- Corrections and amendments
- Refund claims
- Responses to tax demands
Greater automation could reduce manual intervention and shorten processing times, particularly for businesses dealing with refunds and routine compliance issues.
The government’s earlier next-generation GST framework had also highlighted digital filing, faster refunds and easier compliance as major pillars alongside the rate rationalisation exercise.
Why Annual Changes Could Matter for Businesses
Frequent GST revisions can affect companies well beyond the tax amount itself. A change in tax rate may require businesses to alter product prices, update ERP systems, revise invoices, modify contracts and reassess input tax credit positions.
Retailers and manufacturers may also need to deal with existing inventory carrying the earlier rate. The transition following the September 2025 changes, for instance, required adjustments across several consumer categories. Government clarifications were subsequently issued on issues including revised MRPs, input tax credit and treatment of existing stock.
An annual review mechanism could therefore give companies additional time to prepare for changes before the new financial year begins.
Will the GST Council Stop Making Rate Changes During the Year?
Not necessarily.
An annual review framework would not mean that the GST Council could never consider a rate change during the year. The Council would continue to meet and could address significant policy or sector-specific issues when required.
The proposed approach is better understood as a move towards routine annual rate rationalisation, rather than a complete restriction on mid-year GST decisions.
What Could the New GST Reform Phase Focus On?
With rate rationalisation substantially addressed, the next phase could focus on:
- Simpler compliance
- Greater automation
- Faster refunds
- Digital tax administration
- Predictable rate revisions
- Reduced manual intervention
This would shift the emphasis of GST reform from changing tax rates to improving how the tax system operates.
A More Stable GST Framework Ahead
The shift towards annual rate revisions would mark a change in the way India manages its indirect-tax system. GST would still remain flexible enough for the Council to address major policy issues when required, but routine rate changes could become less frequent.
After the major simplification of tax slabs in 2025, the focus is increasingly moving towards stability, automation and predictable compliance. If the annual review framework is adopted, April 1 could emerge as the key date for future GST rate changes, giving businesses a clearer tax calendar for the financial year ahead.